5 Steps to a Smooth eClose


Updated September 4, 2026
A smooth eClose depends on preparation, the right technology, and a trust infrastructure that holds up after the session ends. Paper closings are slow, error-prone, and increasingly out of step with what borrowers and title teams expect. eClosings have moved well past early adoption. They produce fewer errors, fund faster, and give everyone involved immediate access to documents and information. Lenders, agents, and homebuyers are expecting them.
Here is what lenders and title teams need to do to execute a compliant, fraud-resistant digital close with minimal friction for borrowers.
Key takeaways
- A smooth eClose requires more than the right software. Every participant's identity must be verified, every document must be tamper-evident, and every action in the session must be captured in a defensible audit trail.
- Hybrid eClosings incorporate digital signatures on select documents but still require an in-person appearance. Full eClosings are 100% remote, with eSignatures, eNotes, online notarization, and digital document delivery.
- A successful digital closing requires six components working together: eSignature capability, online notarization, eNote filing, identity verification, eClosing software, and secure document storage.
What makes an eClose "smooth"?
A smooth eClose is fast, accurate, and defensible. Speed matters, but a closing that funds quickly and later gets challenged because identity verification was weak is not smooth. It is a liability.
The teams that run the smoothest closings define the standard across four dimensions:
- Speed: Documents are signed, notarized, and filed without manual delays or back-and-forth.
- Accuracy: Compliance rules are enforced before errors reach the closing table, not after.
- Security: Every signer's identity is verified through credential analysis, biometric comparison, or liveness detection before the session begins.
- Defensibility: Every action in the session is captured in a tamper-evident audit trail that holds up when challenged.
Most eClose friction traces back to a gap in one of these four areas. The steps below address each one directly.
The types of eClosings
There are two main types of eClosings, and the type you run determines how much friction you can eliminate.
Hybrid eClosing: A hybrid eClosing incorporates digital elements, like eSignatures on select documents, but still requires an in-person appearance. Notarization, wet-ink signatures on certain loan documents, and physical document handling remain part of the process. Hybrid closings save time and reduce errors compared to paper, but location remains a constraint.
Full eClosing: A full eClosing means every component is digital: eSignatures, eNotes, online notarization, and digital document delivery. Nothing requires a physical presence. Signers can close from virtually anywhere, including military borrowers on deployment, out-of-state buyers, or anyone who cannot make it to a closing table.
Full digital eClosings unlock the biggest operational gains. They also require the most complete technology stack. If any component is missing, the closing reverts to a hybrid at best.
The parts of an eClosing
A full eClose requires every element of the transaction to move online. Many lenders are still working to bring every component fully digital. Here is what that means in practice:
- eClosing software: Everyone involved needs access to a computer or tablet with an internet connection and video capabilities. Lenders need eClosing software that supports the full digital workflow.
- Digital documents: All documents, including the deed and mortgage agreement, must be available for eSignature. These documents must be formatted so they can be signed, notarized, and filed with the necessary agencies digitally.
- Online notarization: Documents that require notarization need an online notarization platform that handles the process correctly, securely, and in full compliance with state requirements.
- eNote filing: The electronic version of the promissory note must be created, signed, and filed digitally.
- Identity verification: Lenders need a reliable way to verify signer identity before the closing session, through credential analysis, knowledge-based authentication (KBA), or biometric comparison, to meet compliance standards and prevent fraud.
- Secure document storage: Completed closing packages need to be stored in a secure, accessible archive so all parties can retrieve documents and demonstrate compliance after the fact.
The more of these elements a lender has in place, the closer they are to a full eClosing, and the bigger the gains in speed, accuracy, and borrower experience.
Identity verification: the hidden key to a smooth eClose
Identity verification is where most eClose programs have the largest gap. It is also where the biggest fraud risk lives.
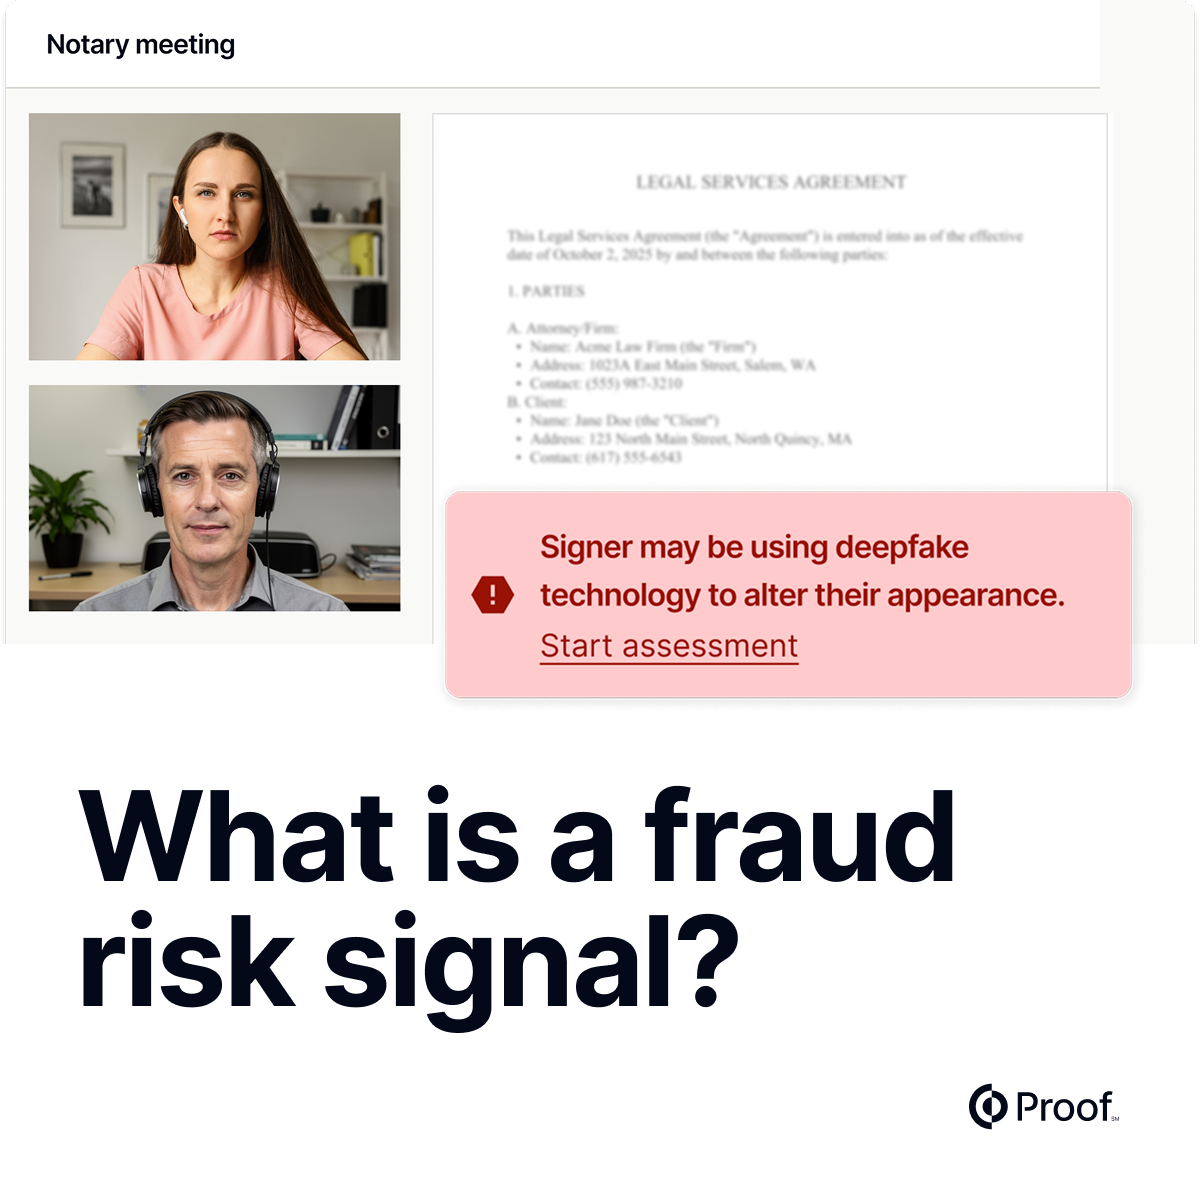
Real estate fraud losses hit $275 million in 2025, up 58% in a single year. Synthetic identities, AI-generated fake IDs, and deepfake video attacks are now operational threats, not theoretical ones. A closing that moves fast but fails to verify who is actually signing is a closing that can be disputed, reversed, or tied to a fraud investigation.
A smooth eClose requires identity verification that goes beyond KBA alone. KBA relies on data that is increasingly available through data breaches and social engineering. The stronger standard combines:
- Credential analysis: Automated checks against the physical and digital security features of a government-issued ID.
- Biometric comparison: A liveness-checked selfie compared against the photo on the credential.
- Live agent fallback: When automated checks cannot confirm identity, a trained agent reviews the session in real time before the closing proceeds.
The Proof Engine runs 25 identity checks in under five seconds. If a check fails, the session does not proceed until the issue is resolved. That is what a defensible audit trail looks like.
5 steps for running a smooth eClose
eClosings have a lot of moving parts. Preparation is the difference between a smooth close and a stalled one. Here are five steps to make sure your team and your borrowers are ready.
Step 1: Create a checklist. Build an easy-to-follow checklist for title agents, real estate agents, and homebuyers so everyone knows what they need and what to expect. A clear checklist reduces last-minute surprises and keeps the process moving. Include technology requirements, document deadlines, and identity verification steps.
Step 2: Do a tech check. Confirm that everyone has access to a computer or tablet connected to the internet, that they have created account logins where needed, and that video is enabled. Homebuyers need video capabilities to complete an eClose. Do not assume everyone has this ready. Verify it ahead of time, ideally 48 hours before closing day.
Step 3: Contact software providers. Errors happen: a failed login, a camera that will not activate, a document that will not submit. Know your support contact before closing day. When a problem surfaces mid-session, you need a fast resolution. Beyond break-fix support, choose a platform that proactively enforces compliance and flags errors before they reach the closing table. The best eClosing software reduces problems before they start.
Step 4: Hold a pre-closing meeting. Do not assume that everyone else will prepare ahead of time. Schedule a quick call with title agents, real estate agents, and homebuyers to run through the checklist and address any questions before closing day. A 15-minute call before closing prevents a 90-minute problem during it.
Step 5: Measure and share successes. Track what works. Document your workflow decisions, which document types required manual intervention, where borrowers needed support, and what compliance flags surfaced. Each close improves your standard operating procedure and builds a defensible record of how your team executes.
Choosing an eClosing platform: what smooth actually requires
Not every eClosing platform delivers a smooth close. The right evaluation criteria go beyond interface design and pricing.
When assessing a platform, confirm it can do the following:
- Enforce state-specific RON (remote online notarization) compliance automatically, without manual review.
- Run identity verification that meets NIST IAL2 standards, including biometric comparison and liveness detection.
- Provide 24/7 notary access so closings are not constrained by business hours.
- Integrate with your existing loan origination system (LOS) and title software.
- Produce a tamper-evident audit trail that documents every action in the session.
- Flag compliance errors before the session begins, not during it.
- Offer a live agent fallback when automated identity checks cannot confirm a signer's identity.
A platform's fastest closing time is meaningless if it cannot legally close a loan in the state where your borrower lives. Evaluate eligibility and integration before you look at the interface.
A smooth eClose is a secure eClose
A smooth eClose is not just about everyone having the right software. It is about ensuring every participant's identity is verified, every document is tamper-evident, and every action in the session is captured in a defensible audit trail. The operational steps and the trust infrastructure have to work together.
eClosings are the standard now. The teams that build full digital closing capability are the ones positioned to compete. Every eClose you run is a step toward a faster, more defensible transaction process.